AuthorsDen.com   Join | Login    
Where Authors and Readers come together!

SIGNED BOOKS    AUTHORS    BOOKS    SAMPLE CHAPTERS    AUDIOBOOKS    eBOOKS    STORIES    ARTICLES    POETRY    BLOGS    NEWS    VIDEOS    SUCCESS    TESTIMONIALS

Featured Authors:  Miller Caldwell, iBethany Peterson, iRobin Ouzman Hislop, iJoy Pedersen, iMargaret Mullings, iMatt Miller, iJeff Ovall, iT. Cline, iJohn DeDakis, iRoxanne Howe-Murphy, i

  Home > Business/Investing > Articles Popular: Books, Stories, Articles, Poetry      Authors: A B C D E F G H I J K L M N O P Q R S T U V W X Y Z     

E D Phillips

 Follow Me  

· Contact Me
· Success story
· Books
· Articles
· Poetry
· News
· Stories
· Blog
· 1,302 Titles
· 6,063 Reviews
· Save to My Library
· Share with Friends!
·
Member Since: Dec, 2008

E D Phillips, click here to update your pages on AuthorsDen!


Books by
E D Phillips


See all Books
by E D Phillips


A Letter to the Federal Reserve Board
by E D Phillips   
Rated "G" by the Author.
     
Last edited: Monday, March 14, 2016
Posted: Monday, March 14, 2016

Recent articles by
E D Phillips

• Spiritism Explained
• Segments from a Bifurcated Life
• AI at Its Best
• July 4, 1776: 250 Years Later
• A Sage or a Saber-Toothed Renegade?
           >> View all

Truth in Lending is essential to a free economy.

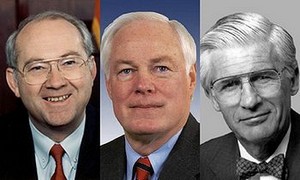
[image: Gramm, Leach, Bliley--puppets for bankers]

Federal Reserve Board
The Federal Reserve
Washington, D.C. 20551
 
Dear FRB Members:
 
It seems incredulous to me that the Federal Reserve has the authority to print money and make it available to large banks for the purpose of lending that money to individuals and to small businesses to stimulate economic growth, but you no authority to see that they do so.  When short term interest rates are very low, for example, banks can borrow that money and direct it into the stock market at very high returns. The incentive is clear:  borrow at 0.25 percent, get a 30 percent return, and--ouila!—they’ve just made 11,900 percent on that money!  Why would they want to do something as mundane as to lend that money to small businesses and to individuals at 4 percent?  When asked why they do not lend money to individuals and to small businesses, bankers reply incoherently “It’s too risky!”  And so, M1 and the economy languish, while M2 and stock prices soar.  Put another way, the rich get richer while the other 90 percent wait and wait for a little trickle down.  Oh, for the bad old days of the Glass-Steagall Act!
 
We might also note that since 2009, U.S. wealth has soared nearly $30 trillion with 90 percent of that total going to those in the top 10 percent.  It would appear to any reasonable person that bankers have the Fed and us right where they want us, thanks to messrs. Gramm, Leach, and Bliley.
 
Still. you are not powerless in this scenario.  You could have a greater voice in creating new jobs, new incomes, new tax revenues, and in reducing budget deficits and debt.  Here is a start:
 
Track (M2 – M1) and show the velocity of that measure, or at least the opportunity cost of money that flows from it.  Show how it increases at the expense of the economy; how money intended for job growth actually goes into wealth growth for the wealthy; and show which banks are denying economic growth in favor of helping their wealthy clients.  We know that new money must be put into circulation if it is to create economic growth.  Conversely, new money that flows into savings and investments has no effect at all on GDP growth, job growth, income growth, tax revenue growth, or deficit reduction.  If only $1 trillion of M2 – M1 since 2009 had gone into M1, the economy would have grown by an additional $6 trillion in GDP, by $5.1 trillion in more personal incomes; by 4.8 million more jobs, and tax revenues at all levels would have increased by $2.4 trillion.
 
A second suggestion is to make a lot more money available to community banks, to credit unions, to co-ops, and to the Small Business Administration.  They are the real job creators.
 
The Fed needs to represent the 90 percent of residents who are being denied their just due.  Of the 200 to 300 Ph.D. economists in your domain, at least 90 percent of them know this bit of elementary economics.  But none to my knowledge are vocal about it.  Do they fear for their jobs? 
 
Empowering America with the truth is the best form of job security for everyone.  It may take a lot of truth to stimulate bankers to act in the country’s interest.  But it’s worth a try.
 
Sincerely,
 
 
 s/
Edward Phillips
 

Web Site: AuthorsDen.com


Want to review or comment on this article?


Need a FREE Reader Membership?
Reviewed by Ronald Hull
Reviewed on March 15, 2016
Another fine article on the Federal Reserve and the printing of money and its distribution. What is sad is most of the public just doesn't understand what is happening in spite of your very cogent and clear articles pointing out the problems and how they can be fixed.

For some silly reason so many of the conservative ilk still believe that unrestrained capitalism is good because it "creates." Like you often state, it creates monopolies, restricts competition, reduces individual entrepreneurship, and forces us into a communistic "one size fits all."

Ron

Reviewed by Odin odin@aflx.com
Reviewed on March 14, 2016
For someone that is just getting acclimated to the machinations of economics ( I was, after all, with my head up my ass as a Hollyweirdite slave for 40 years) so, please, tell me, why can't the fed loan money with a caveat or two that says, "you cannot use this money being loaned to you for the purpose of loans to small businesses to feather your bed by investing in the market to bolster the return for your stock holders?" I don't get it. Yet, save the efforts of people like Elizabeth Warren, who is pushing the question into possible legislation. I'm relatively naive, so please enlighten me. Terrific article.

Reviewed by John Herlihy
Reviewed on March 14, 2016
A very articulate article on an important subject. In addition, let me point out that low interest suits the Fed and the government in other ways. For example, higher interest rates immediately translate into huge sums of money paying off the monthly interest payments on the 9 trillion dollar debt that we are accrued over recent years, a truly staggering amount that simply is not sustainable, much less ever more increased. John

Popular Business/Investing Articles
  1.  Private Equity Firm Sponsors Health Ca
  2.  What Are Friends For?
  3.  Seeking Fairness at Work by Hanna Hasl
  4.  Sorry for the inconvenience and relate
  5.  How To Avoid Personal Liability If you
  6.  Cash Call, A Horror Story For The Smal
  7.  Traffic Counts - KDP Community
  8.  Tariffs v Free Market
  9.  50k and ??????
  10.  Does Policy Create Good Behavior?
  11.  From Queen of Me to Queen of Indy Musi
  12.  Fattening The Businesses/Companies Bef
  13.  Tips for Marketing Your Book this Holi
  14.  6 Pointers to Increase Your Investing
  15.  A $1 Trillion U.S. Infrastructure Plan
  16.  It’s Time to Lower our Corporate Tax R
  17.  Another Merger, Another Loss for Free
  18.  Bad Economic Times Ahead
  19.  Cap Interest Rates: Not the Consumers
  20.  Causes and Consequences of Income Ineq
  21.  Recession Clouds on the Horizon
  22.  Meet Warren Buffett
  23.  My Black Swan for Black and White Thin
  24.  The Importance of Book Covers on Autho
  25.  Economic Facts v Fiction

Free Book Review Program
Select a book to read and review today!

Beyond Ego - The Inner Compass of Conscious Leadership by Thor Olafsson

Once walked, the path of the Inner Compass leaves everyone transformed. Uncover a future with unlimited leadership possibilities. Master your ego https://www.amazon.co.uk/dp/B09ZRRPFW5/  
Member BookAds

How Not to Fail in Business Without Really Trying by Bob Boze

How to be successful in opening and operating your own small business  
Member BookAds

Quick and Easy A to Z Path for Career Success by Margot Dillard

A motivational A to Z listing of words for encouragement and success with quotes and insights.  
Member BookAds