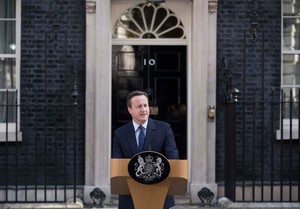
The Fed is ready to add liquidity...
[image: Graeme Robertson, the Guardian]
Brexit: Not to Worry
The Fed is Ready to Add Liquidity…
By the time you read this, the markets around the world will have taken their hits, and the news commentators who are scarcely out of college will be all over the news jabbering like seasoned old windbags about what happened and why. I am not here to add anything to their lengthy discourses in incoherent babble. My job is to track the Fed, and let you know what they will do, why, and what their actions will mean to your pocketbooks. I will only assume that you are one of the 90 percent of Americans and other residents who do not dabble in the stock markets except by way of your 401(k) or similar retirement accounts. If the markets fall by 5 percent, your retirement accounts will fall by a similar amount. But you will also pay for the other 10 percent so they may obtain very cheap loans with which to purchase the same stocks you own, but at the lower discounted prices. Put another way, it will mean another free trip to the public slopping trough for the wealthy while you and I pay for the privilege of feeding them. But it won’t be slop. And it won’t come out of a trough. It will be caviar and champagne at the finest restaurants.
My guess is that the Fed will add about $100 billion of “liquidity” to the banking system. They will make this money available to commercial banks. These banks (7,000 of them) will scoop up this newly printed money and, first, they will fatten up their own accounts, and second, they will send the rest on to their investment banker friends to also scoop and feed and thence to buy all that their greed quotient will allow.
Investment banks make money through a variety of activities that you will likely never see in action. They act as brokers between buyers and sellers of private equity accounts; they underwrite IPOs; arrange mergers and acquisitions (M&A); they manage investment accounts and hedge funds for their wealthy clients; they engage in credit swaps; and they sell their research efforts to their investment clients. Ultimately, money that flows through their accounts end up in adding value to stocks, bonds, real estate, and commodities. These are the same assets that the Fed tallies and keeps track of when determining the wealth of the country. This is known to economists as the investment component of the M2 money supply, or M2 – M1. I can find no evidence that any of this activity has ever produced a single job that is of any importance to anyone who lives among the brethren in the bottom 90 percent of Americans in terms of wealth or income. It’s just that commercial and investment banks get first grab at all newly printed money. Run $100 billion through them, and watch the wealth of those at the high end of the wealth curve rise. That is the beginning and the end of their role as job creators, of GDP boosters, of personal income builders, of tax revenue generators, or of any other aspect of economic life as you and I know it. The number for their impact on all those economic activities is very very close to zero.
The good news to you is this: The dollar will rise against the British Pound and the Euro, by perhaps 2 or 3 percent. The news commentators will lament this outcome as detrimental to our trade. But it amounts to a price reduction for that trip to Europe that you have been saving a life time to take. Go for it!
|



Ron
Love ya!
Jane